The 88% number that explains vet diagnostics
A new MarketsandMarkets report sized the global veterinary point-of-care diagnostics market at $1.19 billion in 2026, projecting $1.72 billion by 2031 at 7.7% CAGR. The operator-relevant data point is buried under the headline: 88% of category revenue is consumables. That ratio explains why instruments get subsidized, why menu expansion compounds, and where the structural risks sit.

Eighty-eight cents of every dollar spent in the veterinary point-of-care diagnostics category in 2025 went to consumables — cartridges, strips, reagents — not instruments. That single data point, buried in a market-sizing report released Tuesday, is the most useful operator lens on the entire vet diagnostics race.
Vet PoC diagnostics sized at $1.19B in 2026, 7.7% CAGR to $1.72B
MarketsandMarkets pegged the global veterinary point-of-care diagnostics market at USD 1.19 billion in 2026, projecting growth to USD 1.72 billion by 2031 at a 7.7% compound annual growth rate. Five other data points from the report deserve attention:
- Consumables = 88.0% of 2025 category revenue. Instruments = 12.0%.
- Immunodiagnostics (lateral flow, ELISA, fluorescence immunoassay) = 84.7% of 2025 technology share.
- Companion animals = 72.5% of 2025 animal-type share. Livestock takes the remainder.
- Asia Pacific is the fastest-growing region at 9.0% CAGR, faster than North America's category baseline.
- Molecular diagnostics — PCR, isothermal amplification, cartridge-based systems — is the fastest-growing technology segment, though still a small share.
The named-vendor list includes the expected leaders (IDEXX, Zoetis, Antech, Thermo Fisher, Virbac, bioMérieux, Neogen) and a longer tail that is more interesting than usual: Enalees (France), EUROLyser Diagnostica (Austria), Bio-Rad, BioNote (South Korea), Shenzhen Mindray Animal Medical Technology (China), Woodley Equipment (UK), FUJIFILM, INDICAL BIOSCIENCE (Germany).
The report itself is a paid product — 450 pages, 420 tables, sold by a market-research firm whose business is selling reports. The headline 7.7% CAGR will get cited in deck slides for the next eighteen months. The numbers underneath are the part worth paying attention to.
What the 88% share tells operators about every diagnostics play
Read literally, the 88% consumables share is a comment on category mix. Read structurally, it explains why vet diagnostics is competed the way it is — and what that means for anyone building, buying from, or investing around the category.
Instruments are a customer-acquisition cost, not a revenue line. When 88 cents of every dollar is recurring consumable spend, the rational vendor strategy is to subsidize hardware to win the workflow. This is why IDEXX, Zoetis, and the broader incumbent set lease, finance, and sometimes effectively give away analyzers to clinics. The model is closer to the printer-cartridge or razor-and-blades dynamic than to capital equipment. Anyone modeling vet diagnostics as a hardware business is modeling the wrong business.
Menu expansion compounds. Once a clinic standardizes on a reference lab or in-house analyzer, every new test the vendor adds to the menu is incremental cartridge volume per existing customer — at near-zero marginal customer-acquisition cost. IDEXX's taeniid tapeworm addition to Fecal Dx, also announced May 26, is a clean illustration. The expansion drives more samples per clinic; it does not require winning new clinics. This is why menu velocity matters more than instrument price in any competitive analysis.
The 84.7% immunodiagnostics share is where the moat sits. Immunoassays — particularly lateral flow and ELISA — are commoditizing at the technology layer. The moat is not the chemistry; it is the assay menu breadth, the analyzer-to-PIMS integration, and the reference-range data accumulated over millions of patient runs. Molecular diagnostics is the fastest-growing segment, but coming off a small base. The next five years are likely an immunoassay-dominated landscape with molecular tools moving into specialist clinics first.
Asia Pacific 9.0% CAGR redraws the global competitive map. Mindray's veterinary arm and BioNote (Korea) are not credible threats to IDEXX in North America today. They are credible threats in markets where IDEXX has thinner direct-distribution coverage. For US-based operators with multi-region expansion plans — pet retail chains entering Asia, vet hospital roll-ups looking at cross-border M&A, animal-health licensing deals — the assumption that the US/EU incumbent set is the only credible global vendor set is starting to weaken.
The companion-animal share will widen, not narrow. The 72.5% companion-animal slice is a function of two compounding trends: continued pet humanization and increased preventive-care utilization in dogs and cats, set against thinner margins and consolidation pressure in livestock veterinary services. Expect that 72.5% to drift up over the forecast period, which means the marginal R&D dollar at every major vendor is being routed toward small-animal menu adds.
Whether the share map holds through 2031
A 7.7% CAGR forecast through 2031 implies the category roughly doubles every nine to ten years, which is consistent with the broader companion-animal health market growth (~8.5% CAGR per Verified Market Research's January 2026 sizing). Two structural risks could bend the curve.
Macro consumer pull-back at the clinic level. Pet owners trading down on visit frequency or skipping wellness panels would compress reference-lab volume directly. The current data does not show that trade-down occurring at scale, but it is the cleanest downside lever to watch.
Tech-stack disruption from AI scribe + cartridge bundling. If AI-scribe vendors (CoVet, Talkatoo, Scribenote) successfully push into clinic order-entry workflows and start bundling diagnostic ordering — particularly with point-of-care vendors offering matched cartridge economics — the reference-lab share could compress. This is a multi-year question, but it is the structural risk that incumbents like IDEXX have to watch most carefully.
Decisions to make on this report: For founders in pet-adjacent diagnostics, the 88% consumables data point is the single best argument for designing a business with assay-menu expansion as the recurring-revenue engine. For investors, it is the cleanest answer to why IDEXX trades at the multiples it does. For independent clinic operators, it is the framework for evaluating any "free analyzer" pitch from a vendor rep — including a careful read of the cartridge-cost ramp once the clinic is committed.
Source: Veterinary PoC Diagnostics Market Worth $1.72 Billion by 2031 via PR Newswire / MarketsandMarkets
Other News
More stories shaping the pet industry this week. From funding rounds and product launches to regulatory shifts and retail strategy, stay ahead of what's driving the market.

Rover names Vik Rajagopal CFO and Jensen Harris president
Rover named Vik Rajagopal chief financial officer and Jensen Harris president of marketplace, product and technology. Rajagopal succeeds Charlie Wickers, and Harris succeeds Brent Turner in the president role.
Fresh Step puts designer scents in litter, starting at Walmart.com
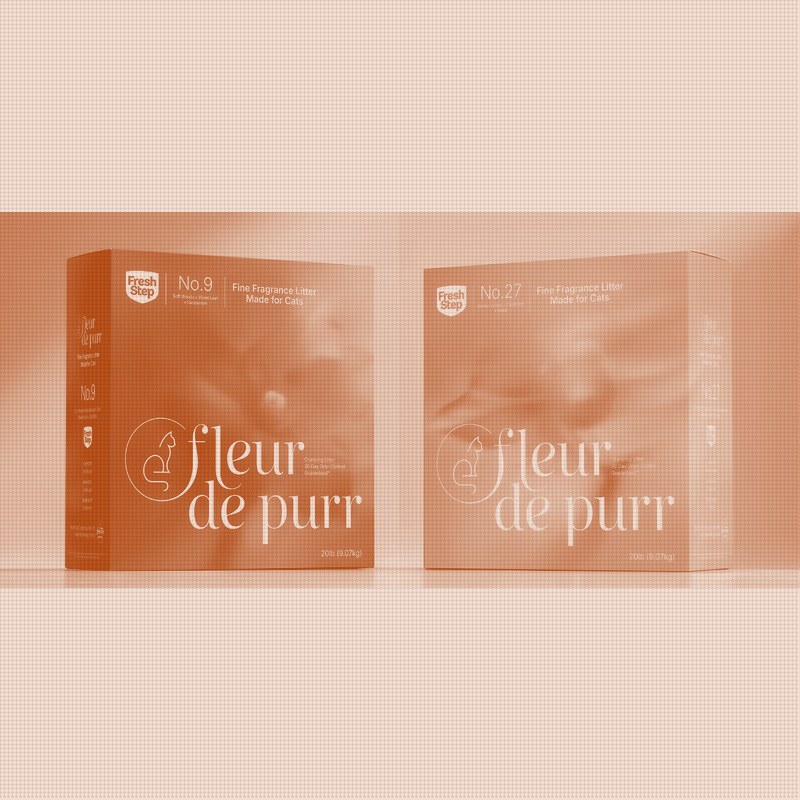
Fresh Step launched Fleur de Purr, a 20 lb clumping litter in two designer-inspired scents with a $20 list price. It is sold exclusively on Walmart.com from November 4th, 2026, reaches Walmart stores December 26th and goes national in April 2027.

Freshpet raises 2026 sales outlook to 12% to 13% on 10% volume growth
Freshpet raised its 2026 net sales growth outlook to 12% to 13% after third-quarter net sales rose 10.0% to $317.8M on 10.0% volume growth. Adjusted Gross Margin reached 50.0% and adjusted EBITDA was $64.5M.