IDEXX raises 2026 guidance a third time as Q3 revenue rises 10%
IDEXX grew Q3 revenue 10% to $1.214 billion, with CAG Diagnostics recurring revenue up 11% organically. It raised 2026 revenue and EPS guidance for the third straight quarter and lowered its operating margin outlook to 32.1% to 32.3%.
IDEXX Laboratories grew third-quarter revenue 10% to $1.214 billion and raised its 2026 revenue guidance for the third quarter in a row. It also lowered its operating margin outlook, which the company said includes acquisition-related impacts.
Revenue rose 9.9% as reported and 10.0% organically. CAG Diagnostics recurring revenue, the line built on consumables, reference lab work and rapid tests, reached $967.4 million, up 10.8% reported and 11.0% organic. Diluted earnings per share were $4.01, up 18%, and operating margin was 33.1%, up 100 basis points. IDEXX is based in Westbrook, Maine, and trades on Nasdaq as IDXX.
Mike Erickson, IDEXX's president and CEO, said the company "delivered exceptional third quarter results, reflecting strong commercial execution." He pointed to new products including inVue Dx with FNA and IDEXX Cancer Dx "becoming a multi-cancer panel."
Diagnostics growth outran clinic visits for another quarter
Our second-quarter coverage left two questions for Q3. The first was whether IDEXX would raise guidance a third straight time. It did. According to IDEXX's 8-K exhibit, full-year revenue guidance is now $4.741 billion to $4.767 billion, up from $4.700 billion to $4.745 billion. EPS guidance is $14.96 to $15.16, up from $14.69 to $14.94. Organic growth guidance is 9.3% to 10.0%, up from 8.5% to 9.7%.
The second question was whether CAG Diagnostics organic growth would move back toward 11%. It reached 11.0% for the recurring line. Total organic growth was 10.0%, up from 9% in the second quarter and below the 11% reported in the first. By our math, the revenue guidance midpoint rose about $31.5 million, and IDEXX said about $5 million of that comes from CoVet.
Analysts expected less. An Earnings Whispers preview put consensus at about $1.19 billion in revenue and $3.71 in EPS. IDEXX reported $1.214 billion and $3.96 in comparable EPS, which is roughly 2% above the revenue estimate by our math.
The same preview said U.S. same-store visits fell 1.3% in the prior quarter, with wellness visits down 3.4%, and that management planned for about a 1.5% visit decline in the second half. The CATalyst Council's Vetsource data from 6,595 practices showed all-species clinical visits down 1.9% in Q3, with dogs down 3.3% and cats up 2.7%, as we covered in October. Against that backdrop, IDEXX's U.S. CAG Diagnostics recurring revenue rose 9.6% to $620.3 million.
IDEXX credited net new customers, an 11% larger premium instrument installed base and net price gains. VetLab consumables grew 14% and reference lab services grew 10%. IDEXX did not quantify how much of the growth came from price and mix.
Margin guidance slips as CoVet costs enter the numbers
Operating expenses rose 10% as reported, which IDEXX tied to commercial investment and acquisition costs including the CoVet purchase. The full-year operating margin outlook is now 32.1% to 32.3%, down from 32.3% to 32.5%. Expected margin expansion is 50 to 70 basis points, down from 70 to 90.
EPS guidance still rose. IDEXX now expects about a 2% reduction in average shares, a tax rate near 20.5% versus 21.1% before, and net interest expense near $32 million versus $35 million. Capital expenditures are now expected near $160 million, down from about $180 million.
Erickson described CoVet as part of the software push: "In software, we advanced our capabilities with the acquisition of CoVet, an AI clinical assistant." Veterinary software, services and diagnostic imaging grew 11% in the quarter, led by ImageVue DR50 Plus installations.
Rival test makers now face a larger inVue Dx base
IDEXX placed more than 1,900 inVue Dx analyzers in the quarter and now has an installed base near 11,000. Our earlier coverage put first-quarter placements at about 1,100. Each placement adds an instrument that runs IDEXX consumables. Capital instrument revenue was $51.5 million, flat as reported and organically, while the recurring line grew 11%.
IDEXX's rapid assay products grew 1%. In October, Antech published a JAVMA study in which its Accuplex test detected 94% of Ehrlichia-positive dog samples against 58% for IDEXX's SNAP 4Dx Plus across 309 samples, as we reported. Five of the seven authors work for Antech, which is part of Mars. Zoetis reported flat organic growth in the first quarter with U.S. companion animal sales down 11%, according to our Q1 coverage.
International is where IDEXX grew fastest. International revenue rose 12.4% organically against 8.6% in the U.S., a gap of 3.8 points by our math, and international now makes up about 37% of total revenue. For clinic groups buying consumables, IDEXX cited net price gains in VetLab consumables, rapid assays and reference lab services.
IDEXX will host an investor and analyst session at VMX in Orlando on January 18th, 2027, highlighting its MultiCue Dx point-of-care analyzer.
Other News
More stories shaping the pet industry this week. From funding rounds and product launches to regulatory shifts and retail strategy, stay ahead of what's driving the market.

FTC and 13 states sue to block Covetrus's $3.5B MWI deal
The FTC and 13 state attorneys general sued to block Covetrus's $3.5B purchase of MWI Veterinary Supply, and Covetrus says it will defend the deal in court.
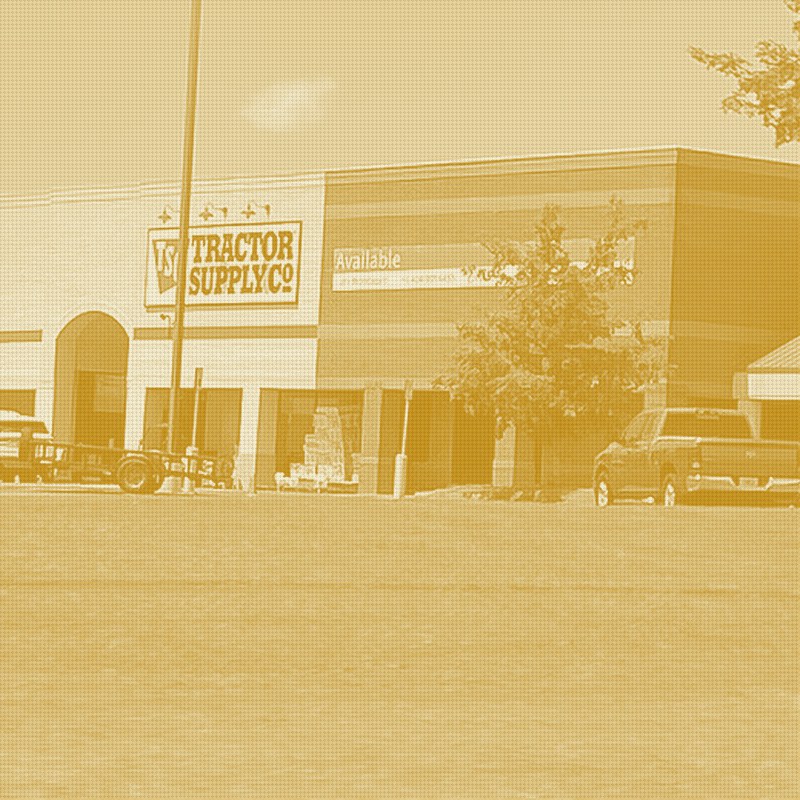
Tractor Supply adds Uber Eats delivery at nearly 2,500 stores
Nearly 2,500 Tractor Supply stores are now orderable through the Uber, Uber Eats and Postmates apps, with pet food and animal care in the assortment. It is the chain's second delivery marketplace after Instacart, and Petco and Pet Supplies Plus already list on delivery apps.

Corbion, MPM and Open Farm win twice at new pet sustainability awards
Corbion, MPM Products and Open Farm each won twice among 17 companies honored in the Pet Sustainability Coalition's first Worldwide awards, open only to accredited members.