Petco Pays Down $75M More Debt as Profit Nearly Triples in Q2
Petco's fiscal second-quarter net income nearly tripled to $38.7 million as comparable sales turned positive for a second straight quarter. The bigger move was on the balance sheet: a fresh $75 million voluntary debt prepayment that brings total paydown to $170 million in nine months.
Net income nearly tripled to $38.7 million in the fiscal second quarter, and the extra cash went toward something more revealing than a buyback: a fresh $75 million paydown on term debt the company has been chipping away at for nine months. Comparable sales at Petco rose 0.6%, marking a second straight positive quarter for a chain that spent much of the past two years explaining why sales kept falling.
Petco's profit nearly triples on positive comps
Petco Health and Wellness Company, the Nasdaq-listed pet retailer trading as WOOF, reported net income of $38.7 million for its fiscal second quarter, up from $14.0 million a year earlier. Diluted earnings per share came in at $0.13, more than double the $0.05 posted in the same period last year.
Net sales held essentially flat at $1.489 billion, but comparable sales rose 0.6%, the second consecutive quarter of positive comps after a stretch where the metric ran negative. Gross margin expanded 37 basis points to 39.7%, and adjusted EBITDA climbed to $122.2 million from $113.9 million, though $6.8 million of that came from a one-time tariff benefit.
The bigger move was on the balance sheet. Petco voluntarily prepaid $75 million of term debt after the quarter closed, bringing total debt prepayments to $170 million over nine months and cutting total debt to $1.48 billion from $1.59 billion. Cash on hand rose to $293.5 million, up $104.8 million year over year, while year-to-date free cash flow reached $60.8 million against $9.9 million a year ago.
CEO Joel Anderson called it "stronger than expected profitability while achieving our second consecutive quarter of positive comps." Store count held nearly flat at 1,377 locations, a net closure of one.
The real story is the balance sheet, not sales
A 0.6% comp gain on flat net sales isn't usually what moves a stock nearly 10% in a session, but WOOF shares gained about 9% on more than double the average trading volume the day results dropped. The debt trajectory is what drove that reaction. Petco went public in 2021 carrying leverage from its 2015 private-equity buyout, and lenders and shareholders alike have been waiting for a quarter where debt fell without sales growth stalling out. This one delivered both.
The timing lines up with Petco's board add a month earlier. Jeffrey Naylor, the former TJX chief financial officer with no ties to the private-equity sponsors who control Petco's board, joined as audit chair on August 1st, one earnings cycle before this report. An independent audit chair overseeing a quarter where debt fell by $75 million and leverage moved toward the company's stated 2x target is close to the governance signal that appointment was built to send.
Compare that to what's happening elsewhere in pet retail. Tractor Supply closed roughly a third of its Petsense stores this year after its pet aisle dragged on results, while Chewy has been raising its own guidance on the strength of its subscription base and vet-clinic push. Petco sits between those two stories: not shrinking like Petsense, not accelerating like Chewy, but grinding out small comp gains while it works down debt from a private-equity-era balance sheet.
For any operator financing a leveraged pet retail concept, the takeaway is that flat-to-slightly-positive comps can still read as a win if the cash goes to debt paydown rather than growth capital. Petco's roughly $140 million capex plan for the year is modest against $1.48 billion in outstanding debt, an allocation choice that trades store growth for balance-sheet repair. That's the opposite bet from Chewy's, and it's the one a company managing toward a leverage target rather than a growth rate is supposed to make.
What Q3 guidance signals for the holiday stretch
Petco reaffirmed its full-year outlook: net sales flat to up 1.5%, adjusted EBITDA of $415 million to $430 million, and 15 to 20 net store closures, all unchanged from the guidance it gave with first-quarter results in June. For the third quarter, it's guiding to net sales growth of 0.4% to 1.0% and adjusted EBITDA of $100 million to $103 million.
Holding full-year guidance steady after two straight positive comp quarters is itself a signal. Management isn't ready to bet the fourth quarter, the one that carries the holiday season and the bulk of annual profit, on the recent trend continuing without confirmation first. The next real test comes with third-quarter results, when analysts look for whether comps stayed positive through the back-to-school and early-holiday setup period, and whether the pace of debt prepayment holds near $75 million a quarter now that leverage is closer to target.
If Petco delivers a third straight positive comp quarter alongside continued paydown, expect the market to start pricing this in as a durable turnaround rather than a low bar cleared twice in a row.
Source: Petco via PR Newswire
Other News
More stories shaping the pet industry this week. From funding rounds and product launches to regulatory shifts and retail strategy, stay ahead of what's driving the market.
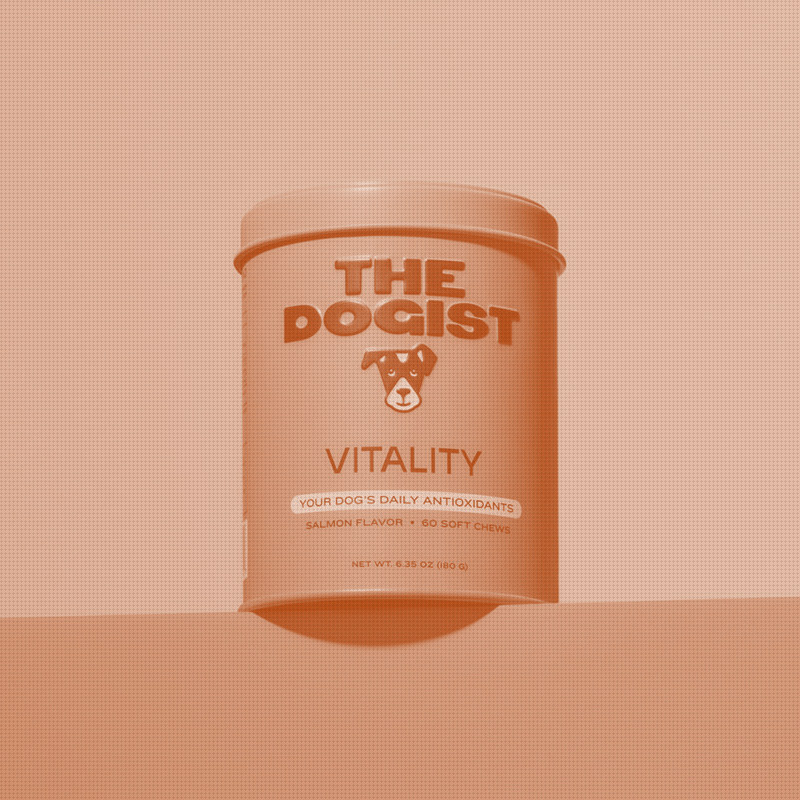
After 13 Years Photographing Dogs, The Dogist Launches Its First Product
Elias Weiss Friedman's picky-eater dog, Elsa, inspired his first product: Vitality, a $35 antioxidant chew developed with a board-certified veterinary nutritionist. Preorders open now ahead of a September 22nd release on The Dogist Company's site and TikTok Shop.
$250M Duffield Pledge Raises the Stakes on Vet Care Access
The Dave & Cheryl Duffield Foundation is committing $250 million over five years to expand nonprofit veterinary care, an initiative it calls the Duffield Big Bet for Pets. The pledge follows PetSmart Charities' $100 million commitment in 2023, pushing dedicated access-to-care philanthropy past $350 million in three years. For operators, the money increasingly funds nonprofit clinic capacity, not just family subsidies.
Loyal's Third Longevity Drug Clears the FDA's First Efficacy Bar
Loyal's LOY-003, a large-breed longevity drug targeting the growth hormone/IGF-1 pathway, has cleared the FDA's Reasonable Expectation of Effectiveness bar, the company's third such acceptance. The milestone de-risks Loyal's broader platform even as its furthest-along drug, LOY-002, still awaits a manufacturing review before conditional approval.