Mars' Venture Fund Bets $6M on Sparkle's Grooming Roll-Up
Sparkle Grooming Co. raised $6 million in strategic financing led by Companion Fund, the Mars Petcare-affiliated venture arm run by Digitalis Ventures. The round adds a corporate strategic investor to a franchise system that still hasn't published an open-unit count or same-store sales figure.
Six million dollars is a rounding error next to the $300 million fund it came from, but the name behind the check is the notable piece here. Sparkle Grooming Co., the four-year-old dog-grooming franchise already sitting on 600-plus sold licenses and a well-documented gap between licenses sold and salons open, just took strategic growth financing from a venture vehicle Mars Petcare runs alongside Digitalis Ventures. For a category built on membership math nobody outside the company has fully verified, a corporate strategic investor changes who gets to ask the hard questions.
Companion Fund backs Sparkle's grooming roll-up with $6 million
Sparkle Grooming Co. announced on September 9th, 2026 that it secured $6 million in strategic growth financing led by Companion Fund, the pet-care venture fund managed by Digitalis Ventures in partnership with Mars Petcare. The company will use the capital to support franchise partner growth, strengthen operational infrastructure, and accelerate national expansion.
Sparkle, founded in 2022, coined the term Quick-Service Pet Care to describe its membership-based grooming model: recurring, standardized visits sold on a subscription rather than the appointment-by-appointment model most independent groomers still run. The company has awarded more than 600 franchise licenses in 24 months. As of this financing, it reports 10 operating salons, with more than 20 expected open by the end of 2026 and 30-plus additional openings planned for 2027.
CEO Ben Crawford, who co-founded the company, called the round significant well beyond the capital, pointing to Digitalis's experience across pet care and animal health. Digitalis Ventures partner Ben Jacobs cited Sparkle's differentiated consumer proposition and a team that understands how to build and scale a franchise system. Neither the release nor the company disclosed a valuation or ownership stake tied to the round.
Why a strategic investor changes Sparkle's disclosure calculus
Companion Fund itself is a departure worth flagging. Mars and Digitalis launched the $300 million second version of the fund in October 2023, describing its focus as founders "leveraging breakthrough science, technology and design," with named earlier investments running toward veterinary diagnostics, fresh pet food, and pet-payment infrastructure, categories built on proprietary technology or product innovation. A brick-and-mortar grooming franchise, whose defensibility rests on operational execution and real-estate density rather than a scientific or technical moat, doesn't obviously fit that thesis on paper. Either Companion Fund is broadening what it considers a defensible pet-care business, or Sparkle's membership economics and internal tech stack convinced the fund the execution itself is the differentiator worth backing.
Mars has skin in dog grooming that predates this round. It owns Wisdom Panel, the DNA test that competes directly with Embark, and it runs Banfield, VCA and BluePearl, giving it the largest veterinary-services footprint of any single owner in the country. A franchise grooming network sits adjacent to that health-services stack rather than inside it. Sparkle doesn't compete with Banfield's exam rooms, but a Quick-Service Pet Care visit is exactly the kind of routine touchpoint that could someday feed a health-monitoring or retail cross-sell relationship, the same logic Chewy used to justify buying Modern Animal's vet clinics.
That's speculative. What isn't speculative is the accountability question The Underbite has raised twice already this year. Sparkle's 500-license and 600-license announcements both omitted an open-unit count, a same-store sales figure, and any Item 19 financial performance representation, the document that would let a prospective franchisee actually underwrite the model. A strategic investor with Mars's brand and reputation at stake has more incentive than a pure financial VC to see those numbers before, not after, a check clears. Digitalis's own public materials describe Companion Fund as backing companies with defensible unit economics, not just growth narratives.
If Companion Fund did underwrite Sparkle's actual salon-level performance before this round, that's a meaningful signal the model works better than the public disclosures alone would suggest. If the fund is buying into the licenses-sold story the same way retail-facing coverage often has, the disclosure gap simply gets a better-funded runway rather than a resolution. Franchisees and franchise brokers evaluating Sparkle now have a data point to weigh either way.
What Sparkle's next license count needs to show
Sparkle's own target is a clean test. Get 20-plus salons open by the end of 2026, up from 10 today.
Also worth tracking is whether Wisdom Panel or another Mars Petcare property shows up in a future Sparkle salon as a bundled offering. That would confirm the cross-sell logic rather than leave it as a reader's inference.
Other News
More stories shaping the pet industry this week. From funding rounds and product launches to regulatory shifts and retail strategy, stay ahead of what's driving the market.
Instinct Science's New AI Bets Proprietary Content Beats ChatGPT
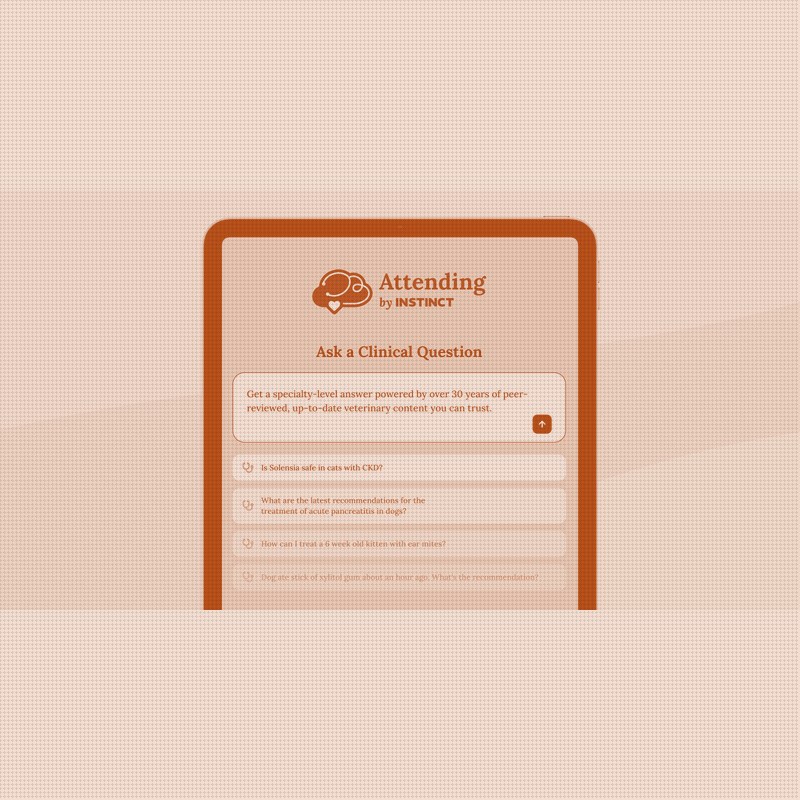
Instinct Science launched Attending, a clinical AI assistant that answers veterinarians' questions using only its own peer-reviewed content, including Plumb's Veterinary Drugs and Clinician's Brief. The tool is in an invitation-only preview ahead of a public showcase at IVECCS this month. It's a bet that proprietary clinical content is worth more as an AI moat than as a subscription business alone.
Temptations Opens a Cat Bodega to Buy Attention, Not Shelf Space
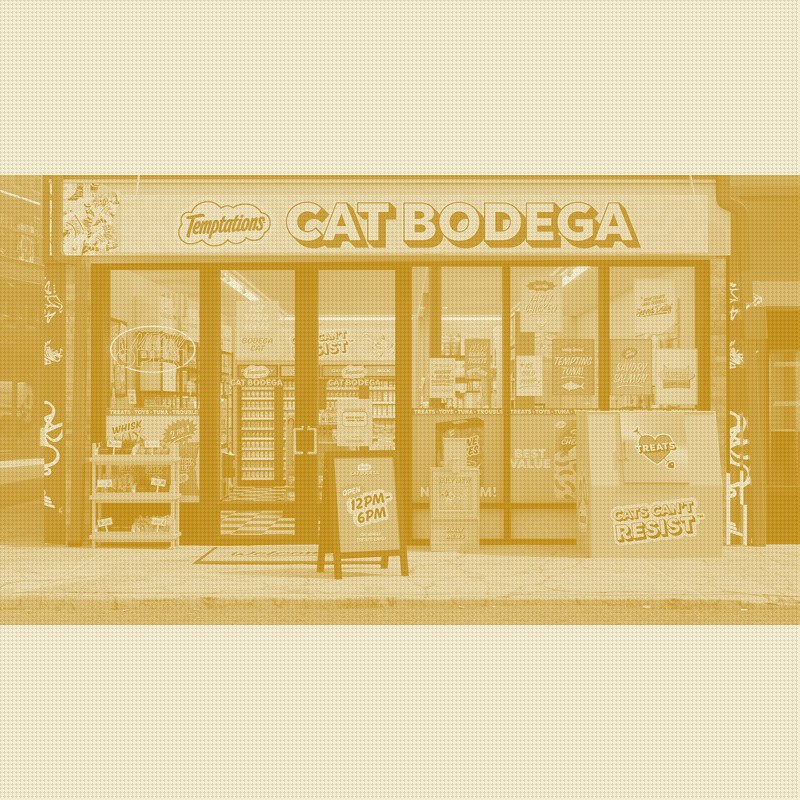
Temptations, Mars's top-selling cat treat brand, opened a free three-day pop-up in Manhattan built around the internet's love of bodega cats. The experiential play signals how a category leader spends on earned attention once shelf space and distribution are already won.
Can Your Dog's DNA Really Explain Its Behavior? Embark Bets $39 On It
Embark launched a $39 Behavior Insights upgrade pairing genetic markers with a year of Dogo training, extending its DNA-test business into recurring engagement. The science behind predicting individual dog behavior from genetics remains unsettled, per a November 2025 UMass Chan study.