Chewy Raises Its Own Guidance Three Months After Cutting It
Chewy raised its full-year fiscal 2026 outlook on Wednesday, three months after cutting it, as autoship retention and vet-care revenue outran the "cautious consumer" thesis that drove the June cut. Petco posted a similarly strong quarter a week earlier, suggesting the pet retail pullback was overstated.
Three months ago, the pet industry's biggest online retailer told investors to expect a slower year. On Wednesday, Chewy reversed itself, raising the same full-year outlook it had trimmed in June, on the back of a second straight quarter of accelerating profit.
Chewy raises its full-year outlook after cutting it in June
Chewy posted $3.33 billion in net sales for the quarter ended August 2nd, 2026, up 7.3% year over year, or 5.7% excluding revenue tied to the SmartPak and Modern Animal acquisitions. Diluted earnings per share came in at $0.20, up six cents from a year earlier. Adjusted EBITDA rose to $226.7 million, a margin of 6.8%, up 90 basis points.
Active customers grew 3.8% to 21.7 million. Autoship, the recurring-order subscription that anchors Chewy's retention model, accounted for $2.82 billion of sales, 84.6% of the total.
In June, Chewy trimmed its full-year sales guidance to a range of $13.40 billion to $13.55 billion, citing a pet consumer pulling back on premium upgrades. On Wednesday, the company moved that range up to roughly $13.46 billion to $13.57 billion and raised its profitability outlook alongside it. CEO Sumit Singh credited "the durability of our recurring revenue base, continued customer growth, and disciplined execution." Shares rose about 0.8% on the report.
The lesson for brands that mirrored Chewy's caution
Guidance from even the category's largest platform turned out to be a noisy signal over a single quarter, not a leading indicator worth building a full annual plan around.
What actually moved wasn't a sudden shift in owner sentiment. Autoship, still 84.6% of sales, kept growing faster than the base business, and the health and services push, layered on through the Modern Animal deal, added revenue the June forecast hadn't fully credited. Recurring orders proved sturdier than the premiumization worry that drove the original cut, and active customer growth held at the same 3.8% pace rather than accelerating, which argues the fix was on the revenue mix, not a consumer mood swing.
That distinction matters for how operators should read "cautious consumer" commentary generally. Chewy's June language, softer premiumization, fewer add-on purchases, described a real behavior among existing customers. It did not describe an exodus, a slowdown in signups, or a category in retreat. The September numbers back that reading up: the same customer base kept buying at the same rate, and the parts of the business built on habit rather than discretionary upgrade, autoship, recurring vet visits, pharmacy refills, carried the quarter. A brand that read June's guidance as "the pet consumer is pulling back" overcorrected. A brand that read it as "trade-up spending is softer than usual" had the more accurate signal all along.
The timing lines up with a second data point in the category. Petco's own second quarter, reported a week earlier, showed profit nearly tripling while the retailer kept paying down debt, a different tone than the "cautious consumer" narrative that dominated pet retail commentary in June. Two of the category's largest platforms beating their own recent caution in the same month reads as a pattern rather than a coincidence.
That's a useful check for any operator still trimming assortment or discounting harder based on a spring thesis built on one data point. The caution wasn't unreasonable to weigh in June. It was premature to lock into a full-year plan.
What the holiday quarter will reveal about durability
The next test is whether this raise holds through the highest-volume stretch of the year. Chewy's new range still sits close to its original April guidance of $13.6 billion to $13.8 billion, so Wednesday's move is closer to a correction than a breakout, and operators should read it that way rather than as fresh evidence of an accelerating category.
Active customer growth is the figure worth tracking next. It has held near 3.8% for two straight quarters. A holiday-quarter acceleration above that range would support the "durable recurring revenue" framing management used on the call. A number that stays flat, or slips, would suggest the September raise leaned more on services revenue and less on a genuinely stronger shopper.
The services mix is the second thing to follow. Chewy Vet Care and the newly folded-in Modern Animal clinics are still ramping, and how much of the next guidance move comes from that segment versus core commerce will tell operators whether the "vet care as growth engine" thesis is holding up or whether it's papering over softer product sales.
Source: Chewy Announces Second Quarter 2026 Financial Results, via Business Wire
Other News
More stories shaping the pet industry this week. From funding rounds and product launches to regulatory shifts and retail strategy, stay ahead of what's driving the market.
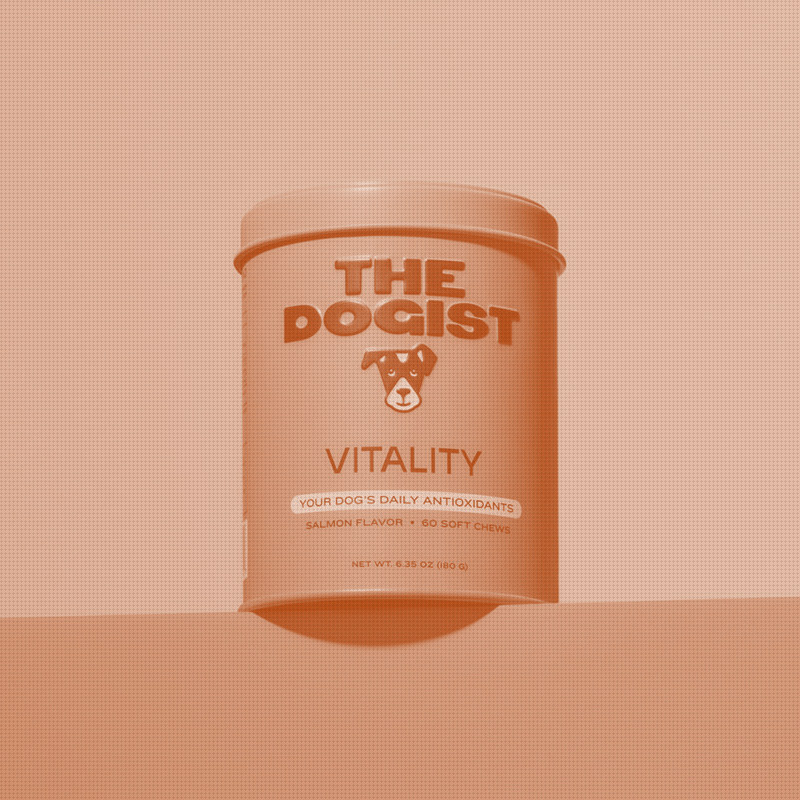
After 13 Years Photographing Dogs, The Dogist Launches Its First Product
Elias Weiss Friedman's picky-eater dog, Elsa, inspired his first product: Vitality, a $35 antioxidant chew developed with a board-certified veterinary nutritionist. Preorders open now ahead of a September 22nd release on The Dogist Company's site and TikTok Shop.
$250M Duffield Pledge Raises the Stakes on Vet Care Access
The Dave & Cheryl Duffield Foundation is committing $250 million over five years to expand nonprofit veterinary care, an initiative it calls the Duffield Big Bet for Pets. The pledge follows PetSmart Charities' $100 million commitment in 2023, pushing dedicated access-to-care philanthropy past $350 million in three years. For operators, the money increasingly funds nonprofit clinic capacity, not just family subsidies.
Loyal's Third Longevity Drug Clears the FDA's First Efficacy Bar
Loyal's LOY-003, a large-breed longevity drug targeting the growth hormone/IGF-1 pathway, has cleared the FDA's Reasonable Expectation of Effectiveness bar, the company's third such acceptance. The milestone de-risks Loyal's broader platform even as its furthest-along drug, LOY-002, still awaits a manufacturing review before conditional approval.